EU VAT e-Invoicing Monitor
Navigate the rapidly changing VAT e-invoicing rules in the EU
This Tax Dossier was last reviewed on 16 November 2026
This dossier provides accurate, reliable and up-to-date information on VAT rules relating to e-invoicing and digital reporting requirements in the European Union.
Outline Tax Dossier
Click the section of your interest or simply scroll down:
- Latest news reports
- Timeline - Adoption of B2B e-invoicing in the European Union
- E-invoicing measures per Member State
- Latest journal articles and opinion pieces
- Key documents at EU level
- Background
Timeline - Adoption of B2B e-invoicing in the European Union
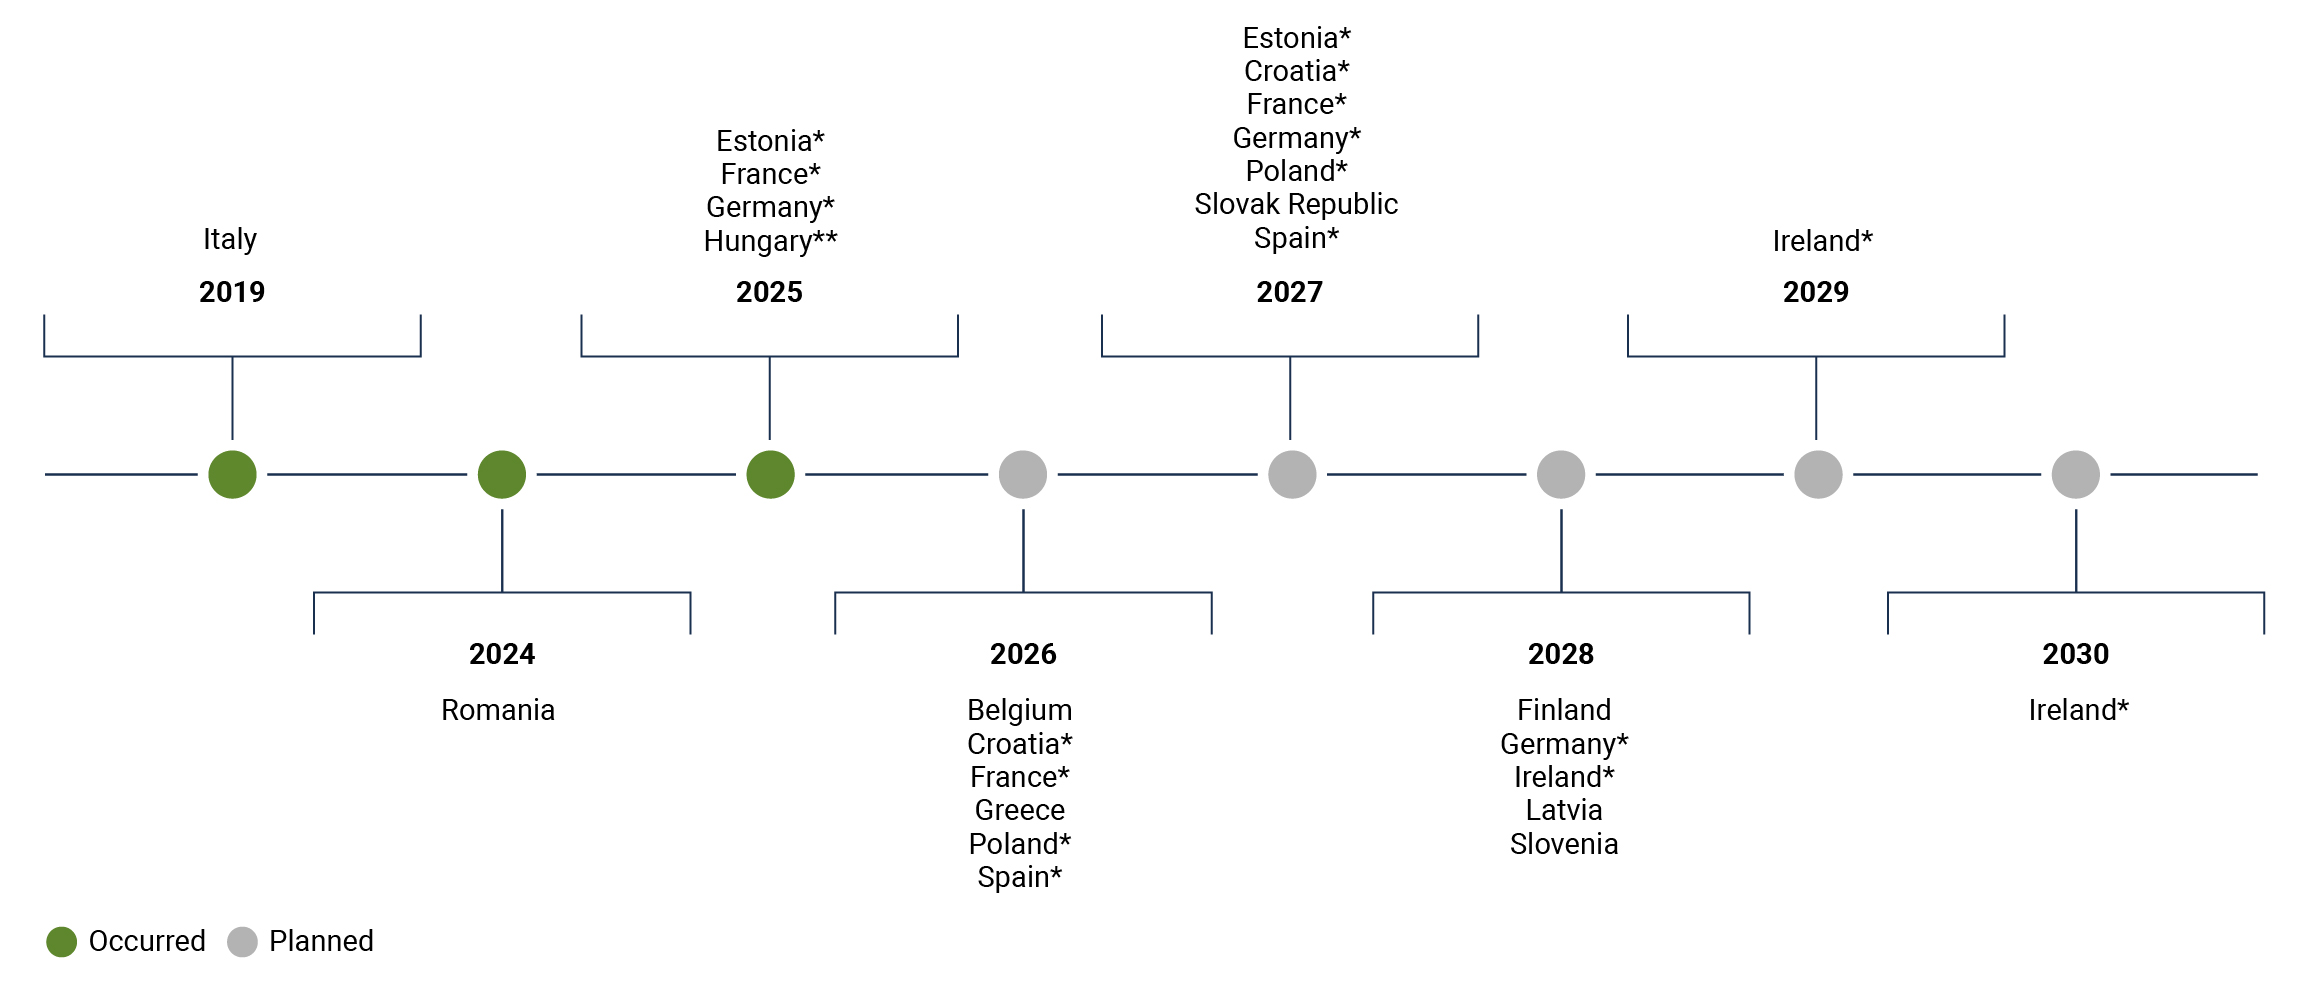
* Implementation in stages. See the table below for details
** This applies only to suppliers in the gas and electricity sector
Notes:
The timeline reflects only Member States that have announced a date of implementation for mandatory or voluntary B2B e-invoicing rules.
B2G and B2C rules are not reflected because:
- B2G e-invoicing is mandatory for EU Member States and has already been implemented throughout the European Union; and
- B2C e-invoicing is voluntary in some EU Member States and has only been implemented mandatorily in Italy and Romania.
Latest news reports
- Ireland - Revenue Updates E-Invoicing and Digital VAT Reporting Implementation Framework (30 October 2026)
- Germany - MoF Issues Guidance on Rules for Electronic Invoicing of Domestic B2B Transactions (21 October 2026)
- France - 2027 Finance Bill in Depth: Government Proposes Simpler VAT Rules for TV Services, E-Invoicing Exemption for Certain Zero-Rated Supplies and Stronger Anti-Fraud Rules (07 October 2026)
- Spain - Spain Set to Implement Mandatory B2B Electronic Invoicing from October 2027 for Large Businesses (06 October 2026)
- Greece - Tax Authorities Postpone Mandatory E-Invoicing Deadline for Smaller Businesses to 2 November 2026 (05 October 2026)
- France - Tax Authorities Release Administrative Guidance on VAT Electronic Reporting (02 October 2026)
- France - Tax Authorities Exclude Certain Press Distribution Services from E-Invoicing Obligation (28 September 2026)
- Bulgaria - MoF Proposes Mandatory Domestic E-Invoicing from 2028 and Higher VAT Registration Threshold (25 September 2026)
- Netherlands - Government Announces Mandatory Domestic E-Invoicing, Digital Reporting (14 September 2026)
France - MoF Reminds Large and Intermediate Enterprises of Mandatory E-Invoicing and E-Reporting from 1 September 2026 (31 August 2026)
E-invoicing measures per Member State
| Country | Implementation status | Date of implementation | National legislation | Name of the e-invoicing system/platform | CTC model | Real-time reporting system | Tax Research Platform resources |
|---|---|---|---|---|---|---|---|
| Austria | B2G: implemented (mandatory) | 1 January 2014 (for invoices sent to federal public administrations) 18 April 2020 (for invoices sent to central government entities) | Federal Public Procurement Act 2018 Austrian ICT Consolidation Act 2012 | Business Service Portal (USP) | Centralized/Peppol | No | Section 11.2.8. Electronic invoicing of the Austria VAT country guide
|
| B2B: not implemented | - | - | - | - | - | ||
| B2C: not implemented | - | - | - | - | - | ||
| Belgium | B2G: implemented (mandatory) | 1 January 2017-1 January 2022 (depending on the region) | Federal Law on Public Procurement of 7 April 2019 Royal Decree of 9 March 2022 | (fully aligned with PEPPOL) | Centralized/ Peppol | No | Section 11.2.8. Electronic invoicing of the Belgium VAT country guide
|
| B2B: implemented (mandatory) | 1 January 2026 | Law of 6 February 2024 Royal Decree of 8 July 2025 on electronic invoicing Royal Decree of 17 December 2025 Law of 10 February 2026 | (fully aligned with PEPPOL) | Post-Audit1 | No | ||
| B2C: not implemented (voluntary) | - | - | - | - | |||
| Bulgaria | B2G: implemented (mandatory, partially) | 1 November 2019 (only receiving and processing for contracting authorities) | Public Procurement Act (SG 86/18) | Central Automated Information System for Electronic Public Procurement (CAIS EPP) | Post-Audit | No | Section 11.2.8. Electronic invoicing of the Bulgaria VAT country guide
|
| B2B: not implemented | 1 January 2028 | Draft legislation from 23 September 2026 | - | Post-Audit + periodic SAF-T | No2 | ||
| B2C: not implemented | - | - | - | - | - | ||
| Croatia | B2G: implemented (mandatory) | 1 July 2019 | Act on e-Invoicing in Public Procurement | (connected to Peppol) | Decentralized 5-corner Peppol model | Yes3 | Section 11.2.8. Electronic invoicing of the Croatia VAT country guide
|
| B2B: in progress (mandatory) | 1 January 2026 - 1 January 2027 | Law on Fiscalization (Official Gazette number 89/25) | (connected to Peppol) | Decentralized 5-corner Peppol model | Yes3 | ||
| B2C: not implemented (voluntary) | - | - | - | - | Yes3 | ||
| Cyprus | B2G: implemented (mandatory, partially) | 18 April 2019 (only receiving and processing for contracting authorities) | The Law of 26 June 2019 on Electronic Invoicing (e-Invoicing) in Public Procurement | Cyprus Government Gateway Portal (Peppol Access Points) | Post-Audit | No | Section 11.2.8. Electronic invoicing of the Cyprus VAT country guide
|
| B2B: not implemented (voluntary) | - | - | - | - | - | ||
| B2C: not implemented (voluntary) | - | - | - | - | - | ||
| Czech Republic | B2G: implemented (mandatory, partially) | 1 October 2016 (only receiving and processing for contracting authorities) | Act 134/2016 Coll. on Public Procurement Ministerial decree 347/2017 Coll. | Národní elektronický nástroj (NEN) (National Electronic Tool) | Post-Audit | No | Section 11.2.8. Electronic invoicing of the Czech Republic VAT country guide
|
| B2B: not implemented (voluntary) | - | - | - | - | - | ||
| B2C: not implemented (voluntary) | - | - | - | - | - | ||
| Denmark | B2G: implemented (mandatory) | 1 January 2005 | Order on Electronic Settlement with Public Administrations, Order 206 of 11.03.2011 Consolidated Law on Public Payments Law on Use of Electronic invoice 1593 of 18/12/2018 | NemHandel | Centralized/ Peppol | No | Section 11.2.8. Electronic invoicing of the Denmark VAT country guide
|
| B2B: not implemented4 | - | - | - | - | - | ||
| B2C: not implemented4 | - | - | - | - | - | ||
| Estonia | B2G: implemented (mandatory) | 1 July 2019 | Accounting Act Value Added Tax Act | Public sector: receives e-invoices individually Private sector: Billberry, E-arveldaja, Finbite, Telema, Unifiedpost | 4-corner model/ Peppol | No |
Section 11.2.8. Electronic invoicing of the Estonia VAT country guide
|
| B2B: in progress (mandatory) | 1 July 2025 (optional for buyers, may demand an e-invoice) Mandatory planned for 2027 | Accounting Act Amendment | Public sector: receives e-invoices individually Private sector: Billberry, E-arveldaja, Finbite, Telema, Unifiedpost | Post-Audit | No | ||
| B2C: not implemented | - | - | - | - | - | ||
| Finland | B2G: implemented (mandatory) | 1 April 2019 (all central government bodies required to receive and process structured e-invoices) 6 April 2021 (extended to cover all public administrations) | Law 241/2019 on Electronic Invoicing | Finnish Government Shared Services Centre for Finance and HR (to centrally process e-invoices) and two more platforms | 4-corner model/ Peppol | No |
Section 11.2.8. Electronic invoicing of the Finland VAT country guide
Section 11.5. Real-time reporting of the VAT country guide
|
| B2B: not implemented5 | - | - | - | - | - | ||
| B2C: not implemented | - | - | - | - | - | ||
| France | B2G: implemented (mandatory) | 1 January 2020
| Decree 2019-748 of 18 July 2019 on Electronic Invoicing in Public Procurement Ordinance 2021-1190 of 15 September 2021 | Chorus Pro | Centralized
| No |
Section 11.2.8. Electronic invoicing of the France VAT country guide
|
| B2B: in progress (mandatory) | Pilot phase in 2025 (gradual implementation starting on 1 September 2026 and 1 September 2027) | Article 26 of the Amending Finance Law 2022-1157 of 16 August 2022 Decree 2022-1199 Order of 7 October 2022 Decree 2024-266 of 25 March 2024 | Accredited Platform (Plateforme Agréée) | Standard 5-corner Peppol | No6 | ||
| B2C: not implemented | - | - | - | Standard 5-corner Peppol | No6 | ||
| Germany | B2G: implemented (mandatory) | 27 November 2020 | Regulation on electronic invoicing in federal public procurement | E-Rechnungs-Portal | Centralized | No |
Section 11.2.8. Electronic invoicing of the Germany VAT country guide
|
| B2B: in progress (mandatory) | 1 January 2025 (for receiving e-invoices) 1 January 2027 (issuing e-invoices for large businesses) 1 January 2028 (issuing e-invoices for all businesses) | Law to Strengthen Growth Opportunities, Investments and Innovation, as well as to Simplify Taxes and Ensure Tax Equity | No centralized platform | Post-Audit | No | ||
| B2C: not implemented (voluntary) | - | - | - | - | - | ||
| Greece | B2G: implemented (mandatory)
| 12 September 2023 | Law 4601/2019 Law 4972/2022 | myDATA platform | Peppol/Clearance | Yes7 | Section 11.2.8. Electronic invoicing of the Greece VAT country guide
|
| B2B: in progress (mandatory) | 2 March 2026 with transitional period until 3 May 2026 (large businesses (turnover > €1 million in 2023)) November 2026 - January 2027 (all other businesses) | Law 5222/2025 Decision A.1044/2026 | Centralized exchange | Yes | |||
| B2C: not implemented | - | - | - | - | - | ||
| Hungary | B2G: implemented (mandatory, partially) | 18 April 2019 (only receiving and processing for contracting authorities)
1 January 2025 (mandatory for national government entities)8 | Act CXXVII of 2007 on Value Added Tax Act LXXXIII of 2018, amending Act CXLIII of 2015 on Public Procurement Government Decree 375/2020 (VII. 30.) | NAV Online Invoicing System | RTIR – Real-Time Invoice Reporting | Yes9 |
Section 11.2.8. Electronic invoicing of the Hungary VAT country guide
|
| B2B: restricted implementation | 1 July 2025 (mandatory only for suppliers in electricity and gas sector) Phased implementation expected in 2028 | Government Decree 273/2007 Government Decree 19/2009 | NAV Online Invoicing System | RTIR – Real-Time Invoice Reporting | Yes9 | ||
| B2C: not implemented | Phased implementation expected in 2028 | - | - | - | Yes9 | ||
| Ireland | B2G: implemented (mandatory, (partially) | 12 June 2019 (only receiving and processing for contracting authorities) | Statutory Instrument 258/2019 | NSSO is partnered with Celtrino (portal for all central government) | Peppol | No |
Section 11.2.8. Electronic invoicing of the Ireland VAT country guide
|
| B2B: in progress (mandatory) | November 2028 (large corporations, domestic transactions) November 2029 (all businesses engaged in intra-EU trade) July 2030 (full implementation) | VAT Modernisation Guidance of Revenue Commissioners | - | Standard 5-corner Peppol | Same implementation timeline as e-invoicing | ||
| B2C: not implemented | - | - | - | - | - | ||
| Italy | B2G: implemented (mandatory) | 6 June 2014 (central government entities) 31 March 2015 (extended to all public administrations) | Decree 148/2018 | Sistema di Interscambio (SDI)10 | Centralized exchange | Yes | Section 11.2.8. Electronic invoicing of the Italy VAT country guide
|
| B2B: implemented (mandatory) | 1 January 2019 | 2018 Budget Law Decree 215/2018 | Sistema di Interscambio (SDI) | Centralized exchange | Yes | ||
| B2C: implemented (mandatory) | 1 January 2019 | 2018 Budget Law Decree 215/2018 | Sistema di Interscambio (SDI) | Centralized exchange | Yes | ||
| Latvia | B2G: implemented (mandatory) | 1 January 2025 | Cabinet Regulation 154 Public Procurement Law | Central platform eAddress (maintained by the State Digital Development Agency (VDAA) | Post-Audit | No | Section 11.2.8. Electronic invoicing of the Latvia VAT country guide
|
| B2B: in progress (mandatory) | 1 January 2028 | Accounting Law Amendments to the Accounting Law | - | Post-Audit | Expected in January 2028 | ||
| B2C: not implemented | - | - | - | - | - | ||
| Lithuania | B2G: implemented (mandatory) | 1 July 2017 (central, regional local authorities) 1 July 2024 (extended to all public entities) | Law on Public Procurement of the Republic of Lithuania | SABIS (connected to Peppol) | Centralized/ Peppol | No | Section 11.2.8. Electronic invoicing of the Lithuania VAT country guide
|
| B2B: not implemented | - | - | - | - | No | ||
| B2C: not implemented | - | - | - | - | No | ||
| Luxembourg | B2G: implemented (mandatory) | 18 April 2019 | Law of 16 May 2019 on Electronic Invoicing in the Context of Public Procurement and Concession Contracts | Peppol | No | Section 11.2.8. Electronic invoicing of the Luxembourg VAT country guide
| |
| B2B: not implemented (bill not yet adopted) | 1 January 2028 (large businesses) 1 July 2028 (medium-sized businesses) 1 January 2029 (all other businesses) | Draft bill amending the law of 16 May 2019 on electronic invoicing and the VAT law of 12 February 1979 | - | - | - | ||
| B2C: not implemented | - | - | - | - | - | ||
| Malta | B2G: adopted11 | 1 April 2020 | Legal Notice 403 of 2018 Legal Notice 404 of 2018 Financial Administration Act Audit Act Local Councils Act | No e-invoicing platform in place | Peppol | No |
Section 11.2.8. Electronic invoicing of the Malta VAT country guide
|
| B2B: not implemented | - | - | - | - | - | ||
| B2C: not implemented | - | - | - | - | - | ||
| Netherlands | B2G: implemented (mandatory, partially) | 18 April 2019 (only to central government) | Law of 20 December 2017 amending the Public Procurement Law 2012 | Peppol | No | Section 11.2.8. Electronic invoicing of the Netherlands VAT country guide
| |
| B2B: not implemented | 1 July 2030 (domestic B2B transactions) | - | - | - | No12 | ||
| B2C: not implemented | - | - | - | - | - | ||
| Poland | B2G: implemented (mandatory) | 18 April 2019 (for contracts valued at EUR 30,000 or more) 1 August 2019 (for all contracting authorities) | Act of 9 November 2018 on Electronic Invoicing in Public Procurement, Concessions for Construction Works or Services and Public-Private Partnerships | National e-Invoicing system (Krajowy System e-Faktur -KSeF) | Centralized & Clearance/ Peppol | No | Section 11.2.8. Electronic invoicing of the Poland VAT country guide
|
| B2B: in progress (mandatory) | 1 January 2022 (voluntary) 1 February 2026 (for large businesses) 1 April 2026 (all businesses) 1 February 2027 (micro-businesses with monthly sales not exceeding PLN 10,000) | Act of 16 June 2023 amending the Act on Tax on Goods and Services and Certain Other Acts Act of 9 May 2024 | National e-Invoicing system (Krajowy System e-Faktur -KSeF) | Centralized & Clearance/ Peppol (as of 1 February 2026) | Yes13 | ||
| B2C: in progress (voluntary) | 1 January 2022 (voluntary) 1 February 2026 (for large businesses) 1 April 2026 (all businesses) 1 February 2027 (micro-businesses with monthly sales not exceeding PLN 10,000) | Act of 16 June 2023 amending the Act on Tax on Goods and Services and Certain Other Acts Act of 9 May 2024 | National e-Invoicing system (Krajowy System e-Faktur -KSeF) | Centralized & Clearance/ Peppol (as of 1 February 2026) | No | ||
| Portugal | B2G: implemented (mandatory) | 1 January 2021 | Decree 123/2018 Law 111-B/2017 Law 82/2023 | Centralized | Yes | Section 11.2.8. Electronic invoicing of the Portugal VAT country guide
| |
| B2B: not implemented (voluntary)14 | - | - | - | - | Yes15 | ||
| B2C: not implemented | - | - | - | - | Yes | ||
| Romania | B2G: implemented (mandatory) | 1 July 2022 | Law 199/2020 on Electronic Invoicing in Public Procurement Implementing Rules of the Fiscal Code (Law 227/2015) | RO e-Factura system | Centralized | Yes16 | Section 11.2.8. Electronic invoicing of the Romania VAT country guide
|
| B2B: implemented (mandatory) | 1 January 2024 (issuance of e-invoices for all businesses) 1 July 2024 (issuance and reception of e-invoices for all businesses) | Law 296/2023 Regarding Fiscal-Budgetary Measures to Ensure the Financial Sustainability of Romania in the Long Term | RO e-Factura system | Clearance/ Centralized | Yes16 | ||
| B2C: implemented (mandatory) | 1 January 2025 | Emergency Ordinance 69/2024 | RO e-Factura system | Clearance/ Centralized | Yes16 | ||
| Slovak Republic | B2G: implemented (mandatory, partially) | 1 August 2019 (only receiving and processing for contracting authorities) | Act 215/2019 on the Guaranteed Electronic Invoicing and the Central Economic System and on Amendments to Certain Laws | IS EFA (Informačný systém elektronickej fakturácie) – in progress | Post-Audit | No | Section 11.2.8. Electronic invoicing of the Slovak Republic VAT country guide
|
| B2B: in progress (mandatory) | 1 January 2027 | Bill No. 385/2025 Coll. | IS EFA (Informačný systém elektronickej fakturácie) – in progress | Post-Audit | No | ||
| B2C: not implemented | - | - | - | - | - | ||
| Slovenia | B2G: implemented (mandatory) | 1 January 2015 | Act Amending the Provision of Payment Services to Budget Users Act | Centralized/ Peppol | No |
Section 11.2.8. Electronic invoicing of the Slovenia VAT country guide
| |
| B2B: in progress (mandatory) | 1 January 2028 | Act on the Exchange of Electronic Invoices and Other Electronic Documents | - | - | - | ||
| B2C: not implemented | - | - | - | - | - | ||
| Spain | B2G: implemented (mandatory) | 1 January 2015 | Law 25/2013 | FACe platform | Centralized | Yes17 |
Section 11.2.8. Electronic invoicing of the Spain VAT country guide
|
| B2B: in progress (mandatory) | 6 October 2027 (businesses with turnover exceeding €8 million in the preceding calendar year) 6 October 2028 (all other businesses) | Law 18/22 Royal Decree 1007/2023 Royal Decree 254/2025 Royal Decree 15/2025 Royal Decree 238/2026 Order HAC/1028/2026 | Private platforms Public E-Invoicing Solution (Solución Pública de Facturación Electrónica, SPFE) | Post-Audit; Immediate Supply of Information (SII) | Yes17 | ||
| B2C: not implemented | - | - | - | - | - | ||
| Sweden | B2G: implemented (mandatory) | 1 April 2019 | Act on Electronic Invoicing in Public Procurement (2018:1277) Ordinance for Accounting Ordinance for Electronic Information Exchange | No central solution or platform, widespread use of Peppol | Peppol | No | Section 11.2.8. Electronic invoicing of the Sweden VAT country guide
Section 11.5. Real-time reporting of the VAT country guide
|
| B2B: not implemented | - | - | - | - | - | ||
| B2C: not implemented | - | - | - | - | - |
1 Belgium: A bill of 26 October 2026 was submitted to the Belgian Parliament introducing near-real-time VAT transaction reporting from 1 January 2028.
2 Bulgaria: Bulgaria’s Ministry of Finance published a draft legislation on 23 September 2026 introducing mandatory structured e-invoicing, real-time digital reporting with pre-filled VAT returns as of 1 January 2028.
3 Croatia: invoice data must be reported in real-time to the tax authority via ePorezna (eTax), the tax authority portal.
4 Denmark: according to the 2022 Bookkeeping Act, e-invoicing is not mandatory for B2B or B2C transactions, but businesses are required to use certified, cloud-ready bookkeeping systems for real-time reporting, capable of handling structured electronic invoices and generating Standard Audit Files for Tax (SAF-T) when requested by the tax authority. These bookkeeping systems must be able to quickly produce files containing comprehensive financial data to achieve standardized digital reporting. As of 1 March 2027, providers of registered digital bookkeeping systems will have new obligations designed to increase adoption of NemHandel (Denmark’s common infrastructure for exchanging electronic business documents between companies and public authorities).
5 Finland: companies with an annual turnover exceeding EUR 10,000 are entitled to request e-invoices from their suppliers. E-invoicing is intended to be implemented for intra-EU transactions in 2028.
6 France: For transactions outside of the scope of B2B domestic e-invoicing of e-invoicing, there is a separate e-reporting obligation, which requires businesses to transmit detailed transaction data for B2C and cross-border transactions directly to French tax authorities. The implementation calendar is the same as for e-invoicing.
7 Greece: since 1 January 2024, there has been an obligation to transfer accounting data to MyDATA, which is used to pre-fill the VAT return forms.
8 Hungary: Hungary's implementation of e-invoicing for B2G transactions has rolled out over time. By 2026, it will expand to 12 subnational entities. By 2027–2028, it will cover all government entities in Hungary.
9 Hungary: a real-time reporting system has been available since 2018. It was extended in 2021 to cover all B2B, B2C, intra-community and export transactions.
10 Italy: authorization by Decision (EU) 2024/3150 of the European Council to continue using Sistema di Interscambio (SDI) until 31 December 2027.
11 Malta: B2G is not mandatory, but all Central Contracting Authorities must be able to receive and process e-invoices throughout the European Union for procurement above the corresponding thresholds.
12 Netherlands: digital reporting requirements relating to domestic B2B transactions will apply from 1 July 2031.
13 Poland: Mandatory e-invoicing through KSeF replaced traditional VAT reporting in 2026.
14 Portugal: from 1 January 2026, PDF invoices must include a Qualified Electronic Signature (QES), which is a digital signature providing high-level security and authenticity, legally recognized.
15 Portugal: since January 2013, there has been a reporting obligation for all resident taxpayers to submit invoice data to the tax administration. This includes domestic, intra-EU and cross-border transactions. Data must be submitted via an XML file based on the Standard Audit File for Tax (SAF-T) or in real time. From 2027, the submission of SAF-T accounting files will be mandatory.
16 Romania: mandatory e-reporting is automatically performed through the e-Factura system.
17 Spain: The SII (the immediate electronic reporting system for VAT) is mandatory for resident and non-resident businesses with an annual turnover above EUR 6 million. Businesses obliged to comply with the SII are exempted from other periodic reporting obligations. “Veri*Factu” is to be implemented in January 2027. Use of certified accounting software and invoice clearance is mandatory for companies not in the scope of SII.
For more information related to the options exercised by the EU Member States regarding e-invoicing and digital reporting, see VAT Options Exercised by the Member States, section 11.5. Electronic invoicing and digital reporting.
Some e-invoicing abbreviations, definitions and references used in the table:
- Centralized model: e-invoicing model in which electronic invoices are submitted in real time to a national platform that handles their receipt and processing. This central platform then takes care of delivering the invoice to the recipient.
- Clearance model: e-invoicing model which mandates that each electronic invoice is validated or authorized by the tax authority before being delivered to the recipient. Invoices are sent in real time to the government’s central platform, where they are assigned unique identifiers and QR codes.
- Contracting authorities: State, regional or local authorities, or bodies governed by public law or associations formed by one or more of such authorities, or one or more of such bodies governed by public law as defined by article 2(1) of Directive 2014/24/EU of 26 February 2014 on public procurement.
- CTC model: Continuous Transaction Controls model.
- Peppol 4-corner model: e-invoicing model in which electronic invoices or documents are exchanged via Peppol Access Points using the Peppol BIS format. In this set-up, the suppliers send the invoices to their access point, which then transmits the documents to the buyers’ access point, and finally to the buyers themselves.
- Peppol CTC 5-corner model: e-invoicing model that builds upon the 4-corner structure by integrating a central tax authority platform into the system. This government-run platform serves as the fifth component and another level of oversight. This model enables real-time transmission of data to tax authorities.
- Post audit: e-invoicing model in which invoices are transmitted directly from the issuer to the recipient without needing advance clearance from the tax authorities. In other words, the tax authorities do not oversee the issuance and receipt of electronic documents in real time but instead examine the transactions afterward, during audits. In case mandatory e-invoicing or a rigorous CTC model is not in force, post audit would be the model to apply (as transactions and their respective invoices reported in the VAT returns would only be reviewed through audits, if at all).
- Real-time reporting: model by which the invoice is sent to the tax authority in real time and after that is sent to the recipient in an agreed format. There is no validation or forwarding the invoice to the recipient.
Latest journal articles and opinion pieces
Marcos Álvarez Suso
- From Reverse Charge to Real-Time Reporting: The European Union’s Evolving Fight Against Carousel Fraud (18 August 2026)
Eleni Detsaridou
David R. Dietsch
- B2B E-Invoicing in Germany: First Step towards Digital Processes (20 April 2026)
Katharina Artinger
- European Union - Council (22 April 2025)
Angelika Xygka
- Mandatory B2B E-Invoicing in Germany since 1 January 2025 (27 January 2025)
Hans-Martin Grambeck
Christian Amand
- Poland - Mandatory E-Invoicing from 2024 – Key Features of the System and European Background (13 November 2023)
Paweł Selera
- Digitalization of VAT Reporting in Poland (7 November 2023)
Krzysztof Lasiński-Sulecki
- European Union - Proposal for a Secure Digital Reporting Standard for Intra-Community Transactions (27 October 2022)
Sascha Jafari, Marie Lamensch and Marta Papis-Almansa
Key documents at EU level
- Council Directive 2006/112/EC of 28 November 2006 on the common system of value added tax
- Council Directive (EU) 2025/516 of 11 March 2025 amending Directive 2006/112/EC as regards VAT rules for the digital age
- Directive 2014/55/EU of the European Parliament and of the Council of 16 April 2014 on electronic invoicing in public procurement
Background
Electronic invoicing (e-invoicing) refers to digital tax documents with structured data that are machine-readable and exchanged between a supplier and a buyer in a standardized digital format. An electronic invoice (e-invoice) is an invoice that has been issued, transmitted and received in a structured format, enabling automatic and electronic processing.
The European Union began the adoption of e-invoicing through various policy initiatives in the 2010s. One of the most significant developments was Directive 2014/55/EU, which established the rules on electronic invoicing in public procurement. However, its impact on the implementation of e-invoicing in Europe was limited, as it only applied to business-to-government (B2G) transactions, thus excluding the largest portion of the e-invoicing landscape: the business-to-business (B2B) and business-to consumer (B2C) transactions. Moreover, Directive 2014/55/EU did not require businesses to issue e-invoices; it only mandated that public administrations must be able to receive them. For those reasons, a more comprehensive legal framework was needed for B2B and B2C transactions where an invoice is typically required.
Currently, at the EU level, rules on VAT e-invoicing are included in Council Directive (EU) 2025/516 of 11 March 2025 amending Directive 2006/112/EC as regards VAT rules for the digital age and in some of the VAT national laws and regulations, as Member States may determine specific requirements according to their needs and reality. After the entry into force of the VAT in the Digital Age (ViDA) legislative package on 14 April 2025, Member States are allowed to introduce mandatory e-invoicing for domestic B2B and B2C transactions without the need for obtaining a derogation from the European Commission.
See also the VAT in the Digital Age (ViDA) Tax Dossier, available here.